Have you ever felt that the tax authorities were a guest just a bit too greedy at your table? What if, in 2026, you changed the rules of the game? Imagine a scheme where the State, instead of taking from you, becomes your primary partner in building your future financial freedom. This scheme exists, and it has become the favorite among the French since the PACTE law: it is the Retirement Savings Plan (PER - Plan d'Épargne Retraite).
In this year 2026, as the question of retirement remains at the heart of concerns, the PER is no longer just a savings product; it is a true tool for tax engineering. Here is a breakdown of a strategy where every Euro saved today prepares your peace of mind for tomorrow.
The Tax Leverage Effect: How It Works
The greatest PER 2026 tax advantage lies in its deduction mechanism. Unlike a classic tax credit, payments into a PER decrease your taxable income.
The principle is mathematical: the higher your Marginal Tax Rate (TMI), the more your savings effort is subsidized by the State. This is called tax leverage. For a taxpayer in a 30% tax bracket, a €10,000 payment into their PER only "costs" them €7,000 in real cash terms, as they will see their income tax drop by €3,000 the following year.
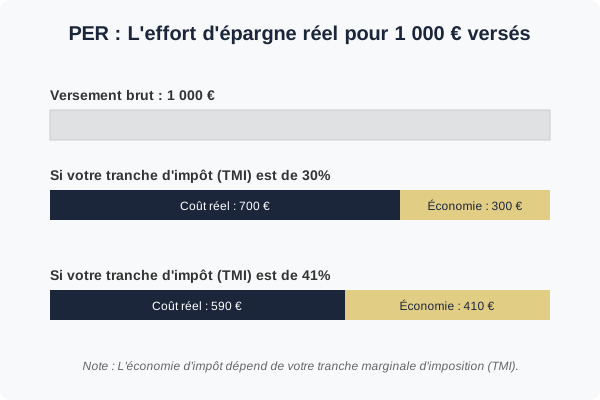
Comparison of the real cost of savings according to your tax bracket.
This is a unique opportunity to have money work for you that would otherwise have been definitively paid to the Treasury.
Simulation: What is the Gain for Your Household?
To understand the impact, let's look at the tax savings generated for a €5,000 payment based on your profile:
- 11% Tax Bracket: Tax savings of €550. Real cost of savings: €4,450.
- 30% Tax Bracket: Tax savings of €1,500. Real cost of savings: €3,500.
- 41% Tax Bracket: Tax savings of €2,050. Real cost of savings: €2,950.
- 45% Tax Bracket: Tax savings of €2,250. Real cost of savings: €2,750.
In 2026, for a senior executive or a business owner in high brackets, failing to use the PER is equivalent to giving up an immediate performance bonus on your savings.
Exit Freedom: The Big Change in 2026
For a long time, retirement products were avoided due to mandatory life annuity exits. The PER has broken these chains. At the time of liquidation, you now have total freedom:
- Capital Exit: You recover all your funds in one go or in installments.
- Life Annuity: You transform your capital into a guaranteed income for life.
- Capital / Annuity Mix: The hybrid solution to secure a minimum income while keeping a pool of liquidity.
Advanced Strategy: Transferring Life Insurance to PER
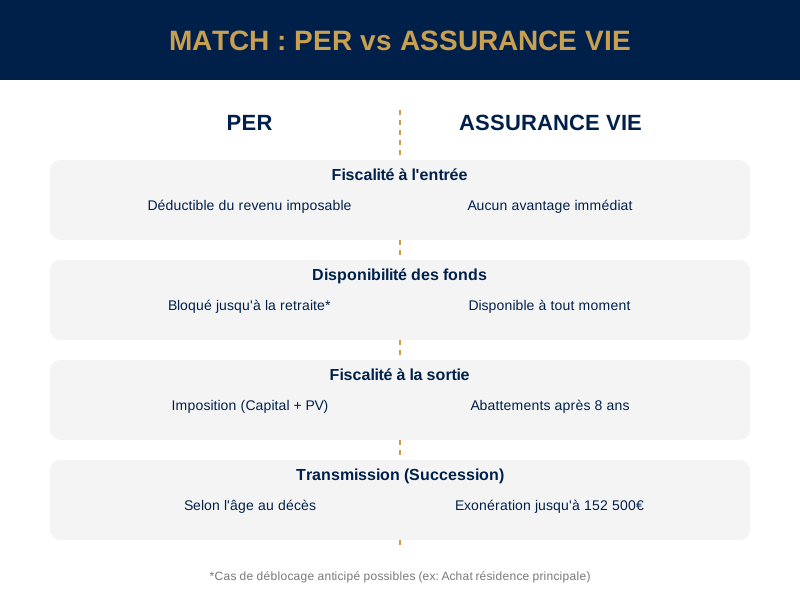
If you own life insurance contracts (Assurance-Vie) older than 8 years, be aware that in 2026, the Assurance-Vie to PER transfer remains a major strategic option. This mechanism allows you to benefit from a doubled tax allowance on your life insurance capital gains, provided the funds are reinvested into a PER and you are more than 5 years away from retirement.
This is a golden opportunity to "purge" the gains accumulated on old, sometimes underperforming contracts to place them into a modern PER, while generating a new tax deduction at the entry.
Expert Opinion: Watch Out for Fees and Assets
Not all PERs are created equal. In 2026, competition is fierce, but vigilance is required. To ensure that the tax advantage is not eaten away by fees, prioritize contracts that have no entry fees and feature reduced management fees.
📘 To go further: 2026 Strategic Wealth Guide
Retirement is prepared today. To understand how to integrate the PER into your global strategy and compare the best contracts on the market, consult our reference guide.
Consult the Wealth Guide 2026 →


Commentaires (0)
Soyez le premier à laisser un commentaire sur cet article.
Laisser un commentaire